Figure
Canada Industrial Figures Q3 2026
October 1, 2026
Demand rebounds, driving largest decline in national availability rate in five years
Executive Summary
- Strong demand drove the national availability rate 30 basis points lower to 5.2% in Q3 2026, the largest quarterly decline seen in five years. This also marked a turning point where the majority of markets now have lower availability rates year-over-year.
- National net absorption surged to 10.3 million sq. ft. in Q3 2026 for the highest quarterly total since Q4 2022. Notably, the bulk of the quarter’s net leasing activity was driven by markets leasing up space within existing inventory.
- Sublease space recorded its first notable quarterly reduction in years, declining by more than 1.0 million sq. ft. in Q3 2026.
- Construction dynamics remain stable with starts and the active pipeline holding at levels in line with recent quarters, keeping construction activity conservative across markets.
- The national net asking rental rate decreased 2.4% year-over-year to $14.77 per sq. ft. in Q3 2026, representing a more moderate pace of decline compared to Q2 2026.
Demand rebounds as net leasing hits multi-year high
National net absorption surged in Q3 2026, totaling 10.3 million sq. ft. of net leasing activity for the highest quarterly total since 2022.
Quarterly net absorption in Q3 2026 was 3.7 times higher than the average pace of the trailing three-year period and has lifted cumulative activity for the year to 18.8 million sq. ft. This puts net leasing for the year-to-date 2026 already well ahead of the full year totals of the prior three years.
Pre-leased space within new supply deliveries accounted for only 2.2 million sq. ft. of net absorption in Q3 2026, highlighting that the bulk of the quarter’s activity was driven by markets leasing up space within existing inventory.
Most markets reported strong levels of demand in Q3 2026, especially in Calgary where quarterly net absorption rose to its second highest on record of 3.8 million sq. ft. from a surge in large bay activity.
While Edmonton was the only market to record negative net absorption in Q3 2026, this was the result of several large blocks of space being returned to market despite otherwise above-average leasing activity.
Strong demand sees majority of markets cross turning point in availability
Higher demand drove the national availability rate lower by 30 basis points (bps) quarter-over-quarter to 5.2% in Q3 2026, marking the largest quarterly decline seen in five years.
Availability rate decreases were broad-based across most markets in Q3 2026. Eight of the 11 tracked markets recorded quarter-over-quarter declines in availability, led by Halifax with a 220 bps decrease and Calgary that dropped by 170 bps.
Q3 2026 also marks a turning point where, for the first time in over three years, the majority of markets are seeing availability rates lower instead of higher on a year-over-year basis.
London remains the primary outlier with a 270 bps year-over-year increase in availability rate, however, the market did see a quarter-over-quarter decrease in Q3 2026.
Sublease space sees notable retreat from record high
National sublease space saw its first meaningful quarterly reduction in over five years in Q3 2026, falling from the record high by 1.1 million sq. ft. quarter-over-quarter to 14.5 million sq. ft.
The largest quarterly declines were seen in Montreal (-574,000 sq. ft.), Toronto (-305,000 sq. ft.) and Edmonton (-291,000 sq. ft.) that accounted for the majority of the national improvement in Q3 2026.
Vancouver recorded the most significant quarterly increase in sublease space in Q3 2026, growing 256,000 sq. ft. quarter-over-quarter.
Despite the notable decrease in sublease space, the national sublet availability rate continues to hold flat at 0.7% in Q3 2026.
Construction pipeline continues to hold steady
Construction starts rose slightly to 5.2 million sq. ft. of new projects in Q3 2026, but activity remains in line with the stabilized pace of the last few quarters.
The new development projects in Q3 2026 were geographically distributed largely in line with market inventory levels, led by Toronto (41.8% of total starts), Montreal (22.8%) and Vancouver (10.9%).
Speculative projects continue to make up the bulk of new construction starts, accounting for 88.4% of total starts in Q3 2026. These projects were mostly concentrated in Toronto and Montreal making up a combined 69.1% of the national speculative starts in the quarter.
With construction starts holding steady, the national under construction pipeline was effectively unchanged quarter-over-quarter in Q3 2026, totaling 25.4 million sq. ft. This represents a conservative 1.2% of inventory, a ratio that has held within a 10 bps range over the past two years.
Construction dynamics remain healthy across all markets
Development in every market in Q3 2026 continues to hold at conservative levels, with nearly all markets building at less than 2.5% of their respective inventory.
Construction in Ottawa totals 8.6% of inventory but is effectively all pre-leased and will have limited impact on available new supply.
Despite the growing prevalence of speculative construction starts, pre-leasing levels on the overall national pipeline has continued to hold steady, with commitments in place on 51.4% of the active development in Q3 2026.
The makeup of the construction pipeline continues to shift in favour of large bay facilities, with mid bay projects also seeing a notably larger share of active construction in Q3 2026.
New supply deliveries on track for lowest annual total in eight years
New supply came in at 5.4 million sq. ft. in Q3 2026, an increase from last quarter’s trough but still holding well below the market highs from a couple years prior.
Speculative projects made up 4.0 million sq. ft. or 73.8% of the new supply that delivered in Q3 2026, with Toronto single-handedly accounting for more than half of that speculative new supply.
Overall, Toronto was the market that saw the largest amount of new supply in Q3 2026, totaling 2.4 million sq. ft. or 45.1% of the national figure. Calgary and Montreal followed accounting for 18.7% and 14.7% of new supply, respectively.
Pre-leasing on the new supply that delivered in Q3 2026 dropped from 52.8% quarter-over-quarter to a seven-quarter low of 40.8%.
An estimated 7.0 million sq. ft. of projects are expected to deliver over Q4 2026, putting national new supply on track to total 19.3 million sq. ft. for the lowest annual total in eight years.
National rent decline moderates as market divergence widens
The national net asking rental rate decreased 2.4% year-over-year to $14.77 per sq. ft. in Q3 2026, reflecting a slightly more moderate annual decrease compared to the 3.8% year-over-year decline in Q2 2026.
Year-over-year rent decreases in Q3 2026 were led once again by the three largest markets of Vancouver (-5.0%), Montreal (-3.4%) and Toronto (-3.1%).
However, five of the 11 tracked markets did record year-over-year rent growth in Q3 2026, with Victoria, London, Calgary and Edmonton seeing annual rent growth of over 2.0%.
On a quarterly basis, the national average rent mostly held flat, decreasing just $0.02 per sq. ft. in Q3 2026. Quarterly rent growth was recorded in four markets, led by the Alberta markets of Edmonton (+3.3%) and Calgary (+2.7%).
National sale prices hold flat while markets varied
The national average asking sale price edged lower in Q3 2026 by 0.2% year-over-year to $312.96 per sq. ft., where it has held within 5% of this level for the past 12 consecutive quarters.
At the market level, sale price growth was more varied, with an even split between markets recording year-over-year growth and decline.
Sale price growth was strongest in Winnipeg and Edmonton where average asking prices rose by 12.0% and 7.3% year-over-year in Q3 2026.
Declines in average sale prices were led by Vancouver (-13.3%), London (-11.3%) and Victoria (-10.5%) in Q3 2026.
On a quarterly basis, the national average sale price decline was more notable, decreasing 1.6% for the largest quarterly drop in seven quarters.
Local Market Insights
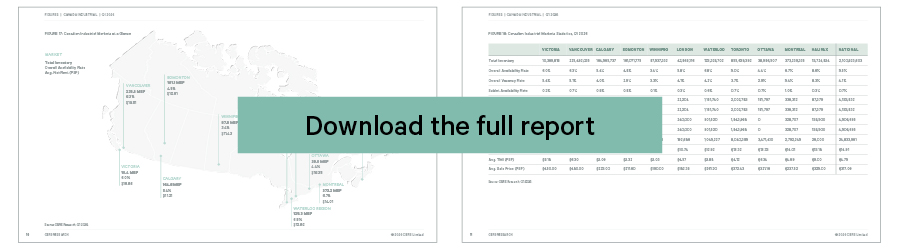
Explore regional industrial statistics in Victoria, Vancouver, Calgary, Edmonton, Winnipeg, London, Waterloo Region, Toronto, Ottawa, Montreal, and Halifax.
Want to receive future reports? | Sign up here.
Contacts


Stay Informed
Stay up to date on relevant trends and the latest research.